LeaderOne Blog
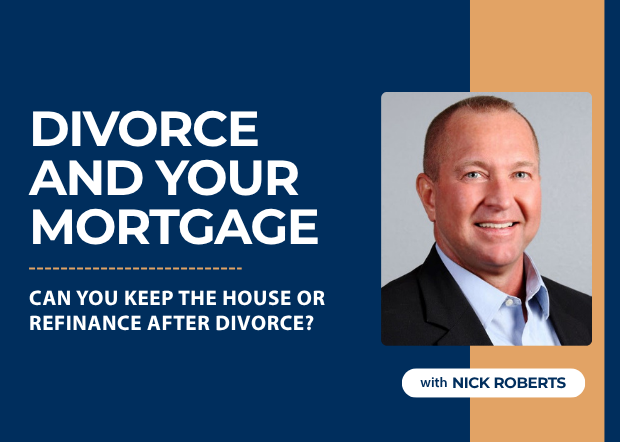
Divorce and Your Mortgage: Can You Keep the House or Refinance After Divorce?
Navigating divorce and wondering what happens to your home? Explore options for keeping your house, refinancing, or buying a new home, and learn how LeaderOne can help you understand your next steps.

Divorce brings both emotional and financial decisions, and your home is often one of the biggest. Questions about the mortgage, home equity, and future housing plans can feel overwhelming, but understanding your options early can help you move forward with greater confidence.
You may be wondering:
- Can I afford to keep the house?
- Will I need to refinance?
- What happens if my name is still on the mortgage?
- Could I qualify to buy a different home?
You don't need to have every answer right away. Learning about your mortgage options now can help you make informed decisions about what comes next.
What Happens to Your Mortgage During a Divorce?
One of the most important things to understand is that ownership of your home and responsibility for your mortgage are separate matters.
A divorce agreement may determine who keeps the property, but it does not automatically remove either borrower from an existing mortgage. Likewise, removing someone's name from the property title does not remove their responsibility for the loan.
Your attorney can explain how your divorce agreement affects property ownership and legal obligations. A loan officer can help you understand the financing options that may be available.
Can You Keep the House After Divorce?
For many people, the family home represents more than a financial asset. It may provide stability, familiarity, and a sense of continuity during a difficult transition.
If keeping the home is important to you, it's worth considering both the emotional and financial sides of the decision. The goal is to make sure the home fits comfortably into your life and budget for years to come.
Depending on your circumstances, options may include:
Refinance the Mortgage Into Your Own Name
A refinance replaces the existing mortgage with a new loan. You would need to qualify based on your financial situation and the requirements of the loan program.
Use a Refinance to Buy Out Your Spouse's Equity
If your home has built equity and your divorce agreement requires a payment to your spouse, a refinance may allow you to access a portion of that equity as part of the settlement. Available equity, loan limits, and qualification requirements will affect whether this approach works for you.
Can You Assume the Existing Mortgage?
In some situations, a loan assumption or another servicer-approved process may be available. Ask your current mortgage servicer whether you can keep the existing loan and what is required to release the other borrower from responsibility. Availability depends on the loan and your circumstances.
Remember to look beyond the mortgage payment. Property taxes, insurance, maintenance, and any homeowners association fees should also be part of your budget.
Should You Sell the House After Divorce?
Keeping the home isn't always the best long-term solution. In some situations, selling can provide greater financial flexibility and a fresh start.
If you're considering purchasing another home, speaking with a loan officer early can help you understand your options, potential budget, and the documents you may need.
You can begin exploring financing before every detail of the divorce is settled. Your loan officer can explain what can be reviewed now and what documentation may need to be finalized before a loan can close.
Can Alimony or Child Support Help You Qualify for a Mortgage?
Alimony or child support may be considered qualifying income if you choose to use it and it meets the loan program's requirements.
Lenders generally need documentation of the arrangement, a history of receiving payments, and evidence that the income will continue. Requirements vary by program, so a newly established support agreement may not immediately provide usable qualifying income.
You do not have to disclose alimony or child support income unless you want it considered for qualification.
A LeaderOne loan officer can help you understand how these requirements may affect your financing options and timing.
How Joint Debt and Credit Can Affect Your Mortgage Options
When evaluating your ability to qualify for a mortgage, lenders may consider obligations such as credit cards, auto loans, and other debts that remain in your name.
Even if a divorce agreement assigns a debt to one spouse, the creditor may still consider both borrowers responsible until the account is refinanced, paid off, or otherwise resolved.
Understanding these obligations early can help you avoid surprises during the mortgage process. Your attorney and loan officer can help you understand how existing debt may affect your plans.
When Should You Talk to a Mortgage Lender During Divorce?
You don't have to wait until every detail of your divorce is finalized to begin exploring mortgage options.
An early conversation with a loan officer can help you understand potential financing scenarios, qualification requirements, estimated costs, and next steps. Having that information early can make important decisions feel more manageable.
Questions to Ask About Your Mortgage During Divorce
Consider asking your loan officer:
- Could I qualify for a mortgage on my own?
- What would my estimated payment and closing costs look like?
- Is there enough equity to support a buyout refinance?
- What documents will I need?
- Could support income or other financial changes affect my timeline?
Understanding the financing details early can help you bring more informed questions to conversations with your attorney.
How LeaderOne Can Help With Mortgage Decisions During Divorce
At LeaderOne, we understand that mortgage decisions during divorce involve more than numbers alone.
We provide clear information, answer your questions, and help you understand the financing options available based on your circumstances. Whether you're hoping to keep your current home or purchase a new one, we're here to help you evaluate your next steps with confidence.
With your permission, we can also communicate with your attorney or Realtor regarding mortgage requirements, documentation needs, and financing timelines.
This article provides general mortgage education and is not legal or tax advice. Consult your attorney or tax professional for guidance specific to your situation. Mortgage options are subject to loan program requirements and credit approval.
About the Author
Nick has spent more than 20 years helping people navigate mortgage decisions during some of life’s biggest challenges, including divorce, separation, and the end of long-term relationships. He understands that these situations are about more than financing; they often involve difficult emotions, uncertain futures, and important decisions that need to be made quickly. His goal is to provide clear guidance, explain your options, and help you move forward with confidence during a challenging transition.